
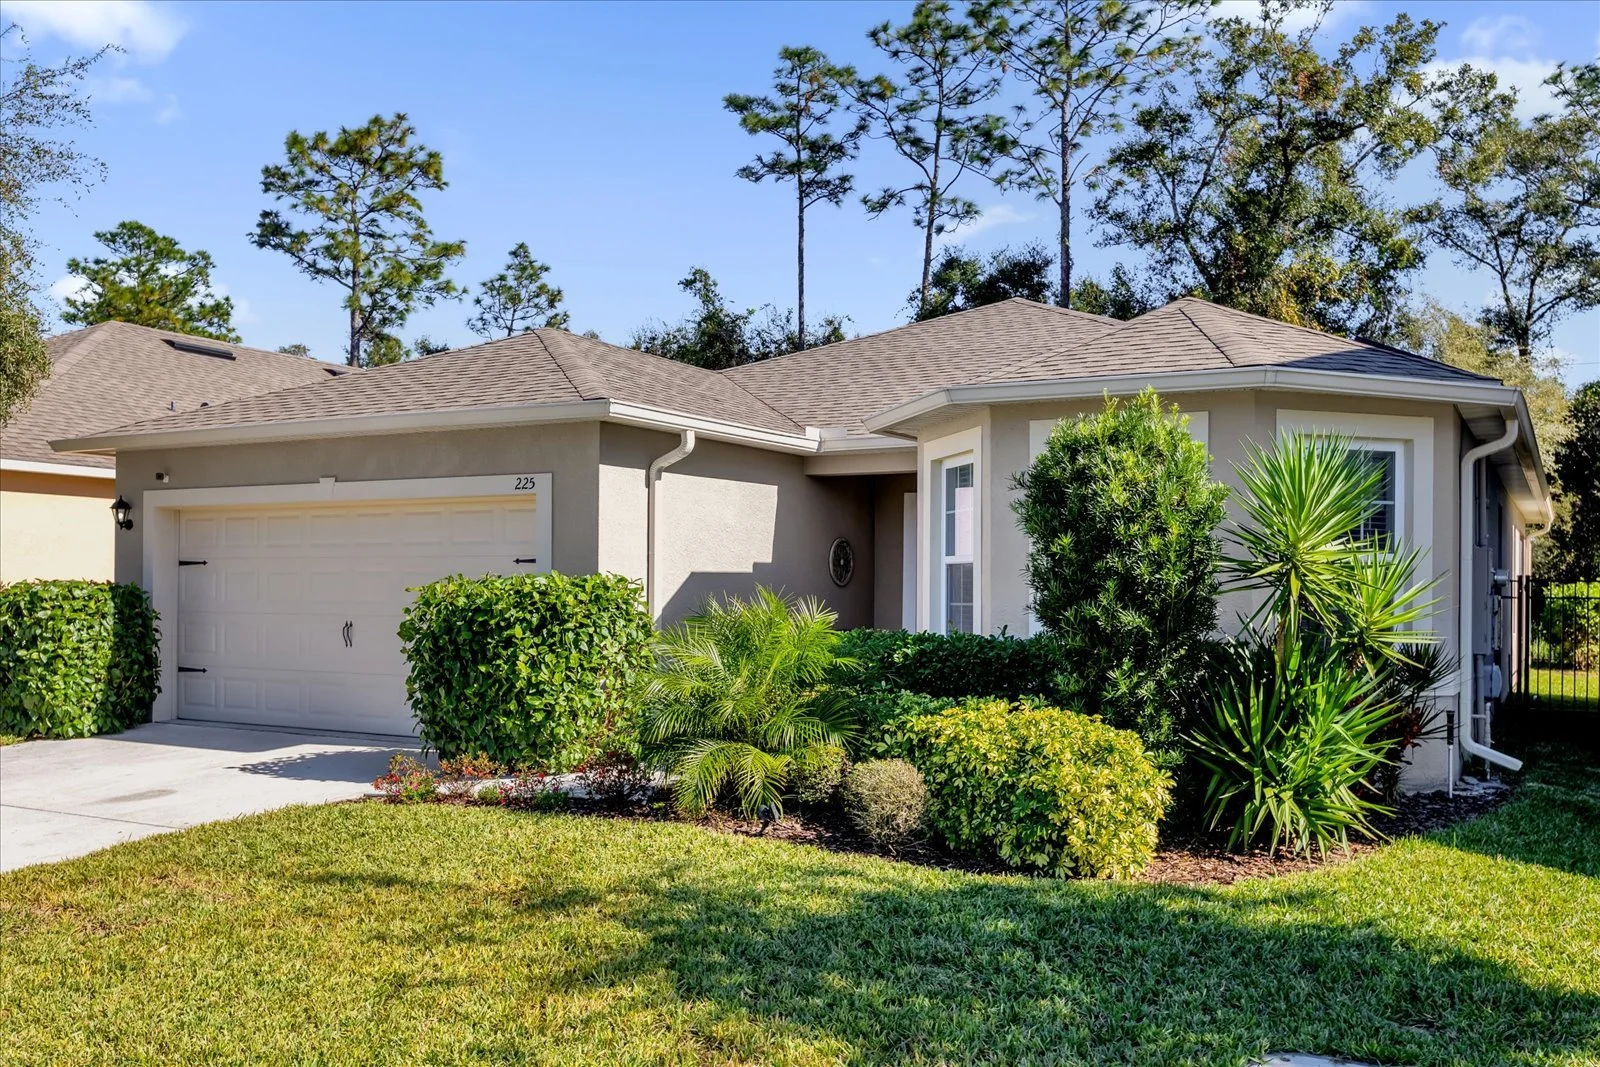
How Much Home Can You Comfortably Afford?
A purchase price is only part of the picture. Your mortgage payment, property taxes, homeowners insurance, HOA fees, and other monthly expenses all affect what a home really costs.
Use the calculator below to explore what different home prices and payments could look like for your budget.
Start With the Payment, Not Just the Price
The amount a lender may approve and the amount that feels comfortable each month are not always the same. A useful affordability plan considers your mortgage payment along with property taxes, homeowners insurance, HOA fees, and the rest of your monthly budget.
The Peterson Group’s affordability calculator helps Central Florida buyers explore a potential purchase range before starting their home search.
See What Your Buying Power Could Look Like
Use your estimated cash in pocket, income, monthly debts, and financing assumptions to explore a potential home purchase range.
Start with your current home value, remaining mortgage balance, and an estimated cost to sell.
These assumptions estimate a potential monthly housing payment and purchase range based on income, debts, financing, taxes, and insurance.
What Your Affordability Estimate Means
Your result is a starting point, not a recommendation to spend the maximum amount shown.
A comfortable home budget should leave room for the rest of your monthly expenses, savings goals, maintenance, and the unexpected costs that come with homeownership.
Monthly Payment Matters Most
A purchase price only tells part of the story. Property taxes, homeowners insurance, HOA fees, interest rate, and loan structure all affect the actual monthly cost.
Approval Is Not the Same as Comfort
A lender may approve you for more than you actually want to spend each month. Your personal comfort level should help shape the home search.
Your Numbers Can Change
Interest rates, insurance costs, property taxes, down payment, and loan terms can all change the range that makes sense.
What Can Change Your Buying Power?
The price of the home is only one part of affordability. These five factors can meaningfully change the monthly cost.
01
Interest Rate
Even a relatively small change in rate can change the monthly payment and the price range that fits your budget.
02
Down Payment
A larger down payment can reduce the amount financed and may also affect mortgage insurance and overall loan costs.
03
Property Taxes
Two homes with the same purchase price can have different tax bills depending on assessed value, exemptions, and location.
04
Homeowners Insurance
Insurance costs can vary significantly based on the property, age, roof, location, coverage, and other risk factors.
05
HOA & Other Monthly Costs
HOA dues, CDD fees, mortgage insurance, and other recurring expenses all affect the total monthly housing cost.
Affordability Is Personal
Two buyers can earn the same income, qualify for the same loan amount, and still have very different ideas of what feels comfortable each month.
Your savings goals, lifestyle, other debts, future plans, and tolerance for housing expenses all matter. The right budget is the one that lets you buy a home without making the rest of your life feel tight.
Possible is not always comfortable.
A good buying strategy defines both what you can afford and what you want to spend each month.
Want to Talk Through Your Numbers?
An affordability calculator can give you a useful starting point, but your actual buying strategy depends on your goals, financing, timeline, and the homes you are considering.
If you want help turning the numbers into a clear plan, we can walk through it with you.